From source line via finding to report
TrusteeTrace reads the entire records and shows what stands out. You mark what is evidence, every finding points to the source line, and with one button it is in your report.
"The owner says the van was sold in March. Is that in the books?"
Yes. On 14 March € 18,500 was written off from Vehicles, against the director's current account. There is no receipt in the bank to match it.
You are a lawyer. The bookkeeping speaks another language.
The answer is usually in the records: in the auditfile, the bank statements, the annual accounts. But anyone who wants to read it has to outsource it today, and wait.
With TrusteeTrace you read it yourself. That includes the questions that come up after the talk with the owner.
Follow the trail
Load the documents
Auditfile, bank statements (MT940 or CAMT.053) and annual accounts as PDF.
See what stands out
The deviating items are ready for you, with an explanation.
Ask the case
Ask your question in plain language. Every amount points to the entries.
Mark the evidence
You decide what counts. The source line goes with it.
Export to your report
Your findings with source references, in one go.
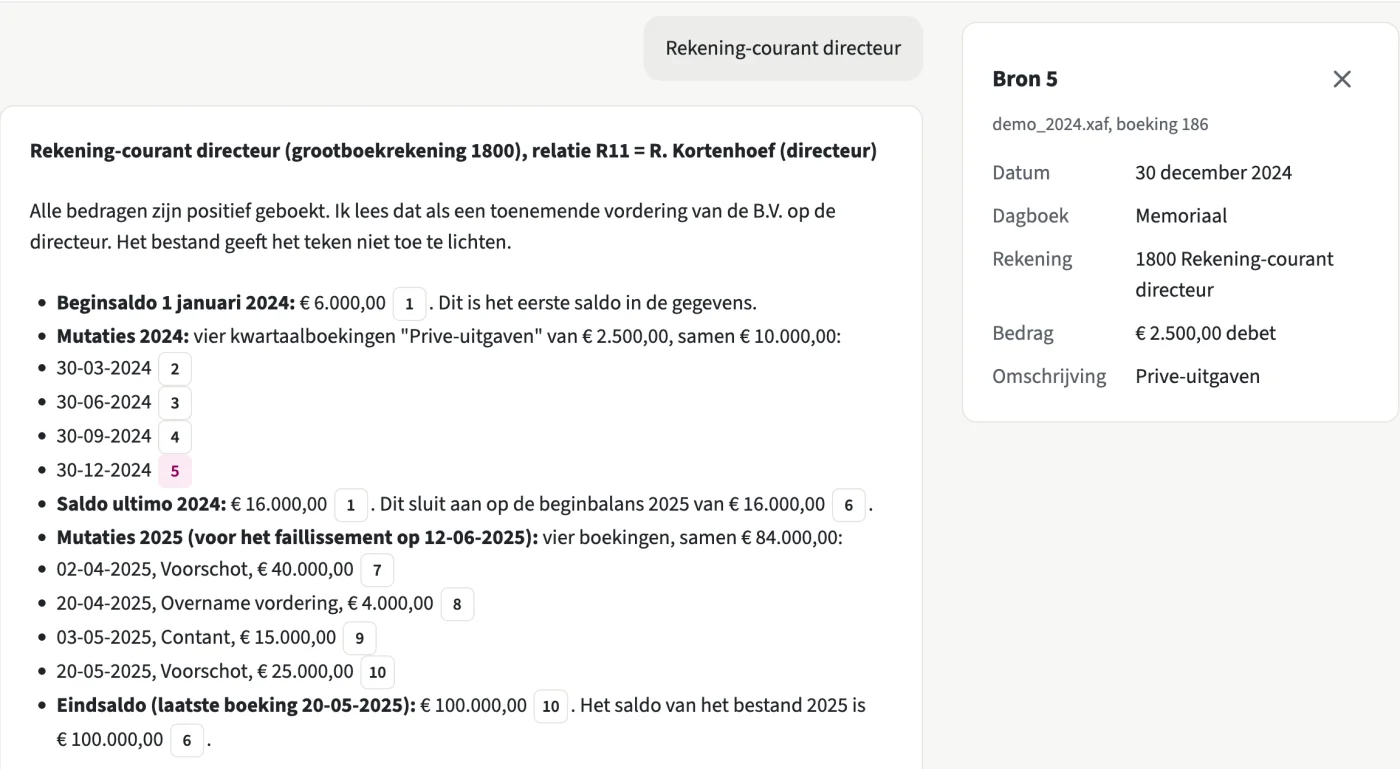
Every amount in the answer has a number. Click it and you see the entry it comes from.
What TrusteeTrace brings to the surface
Related parties
Entries with directors, family and group companies, recognised by IBAN, Chamber of Commerce number or name.
Current account and loans
Every movement in the look-back period, with the balance and the largest amounts.
Sale of fixed assets
Assets written off in the twelve months before the bankruptcy.
Set-off and crediting
Entries with related parties without a bank or cash movement.
Bank against bookkeeping
Bank transactions without an entry, entries without a bank transaction and gaps in the statements.
Annual accounts against records
Differences in equity, result, cash or turnover.
Just ask the case
After a talk with the owner you have questions. Ask them the way you would write them down. The answer names the entries it rests on.
- Which payments went to the director in the last year?
- When was the last rent paid?
- Was the stock sold, and to whom?
Between 1 April 2024 and 14 March 2025, 23 payments were made to J. de Vries, together € 142,380. The largest: € 86,000 on 11 March 2025, three days before the bankruptcy filing.
Your file stays yours
Stored in the EU
Your documents are stored on servers in the EU.
Only you get in
Log in with a password and a code from your phone. Each case is visible only to your firm.
You keep the judgment
TrusteeTrace flags. What counts as evidence and what goes into the report, you decide.
A product of The Auditfile Factory
Decades of experience in banking, financing and IT, and the auditfile inside and out. TrusteeTrace makes that knowledge usable for the trustee: read it yourself, ask yourself, substantiate it yourself.
Do you work in special asset management or restructuring at a lender? Get in touch